
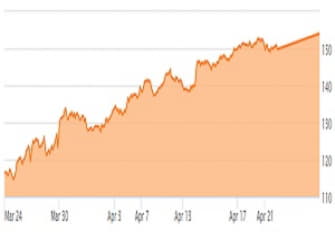
Amid the COVID-19 pandemic, Johnson and Johnson (JNJ) stands out. Not only has J&J demonstrated sound capital allocation decisions with its healthcare portfolio, but its fortress balance sheet and dividend yield make J&J a defensive stock to own amid the uncertainty. J&J's strong quarter highlighted the bull case, along with a comprehensive framework for 2020. The outlined range of potential outcomes based on the available facts today was particularly noteworthy at a time when most companies are outright pulling their guidance and should thus, help reduce the level of uncertainty facing JNJ. Overall, at ~19x P/E, a well-supported ~3% expected dividend yield, and the path toward earnings growth intact from 2021, I rate JNJ a Buy.
Encouraging 1Q Results Offset Lowered Guidance
For the quarter, JNJ reported above-consensus sales of $20.7bn (+3.3% YoY) and headline (adjusted) EPS of $2.30, reflecting operational growth (excluding currency impact) of 4.8%. Adjusted for M&A, operational growth would have been even higher at 5.6%.
READ FULL ARTICLE HERE

