
Summary
- URBN has been pounded of late.
- The company has the balance sheet to survive just about anything.
- And with a very cheap valuation and too-bearish earnings estimates, I think now is an attractive entry point.
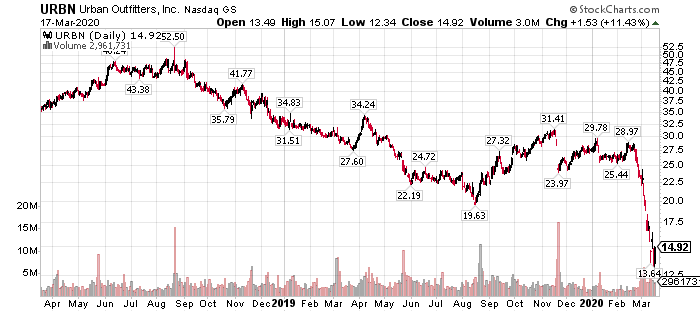
Apparel retailer Urban Outfitters (URBN) has seen its shares cut in half in recent weeks. Of course, there are countless stocks that have suffered similar or worse fates since the coronavirus-driven selloff began, so Urban Outfitters isn’t unique. However, I think shares have fallen far enough that, even taking some recent weakness in margins into account, the stock looks attractive.
Planning for growth, weathering the storm
Urban Outfitters has gone through somewhat of a resurgence in recent years. The company has seen starts and stops with respect to growth, but it recently launched a subscription service wherein customers can rent clothing, return it, and get new pieces shipped to their door. The company has also been investing in its fulfillment capabilities to enhance its digital channel.
Source: Investor presentation
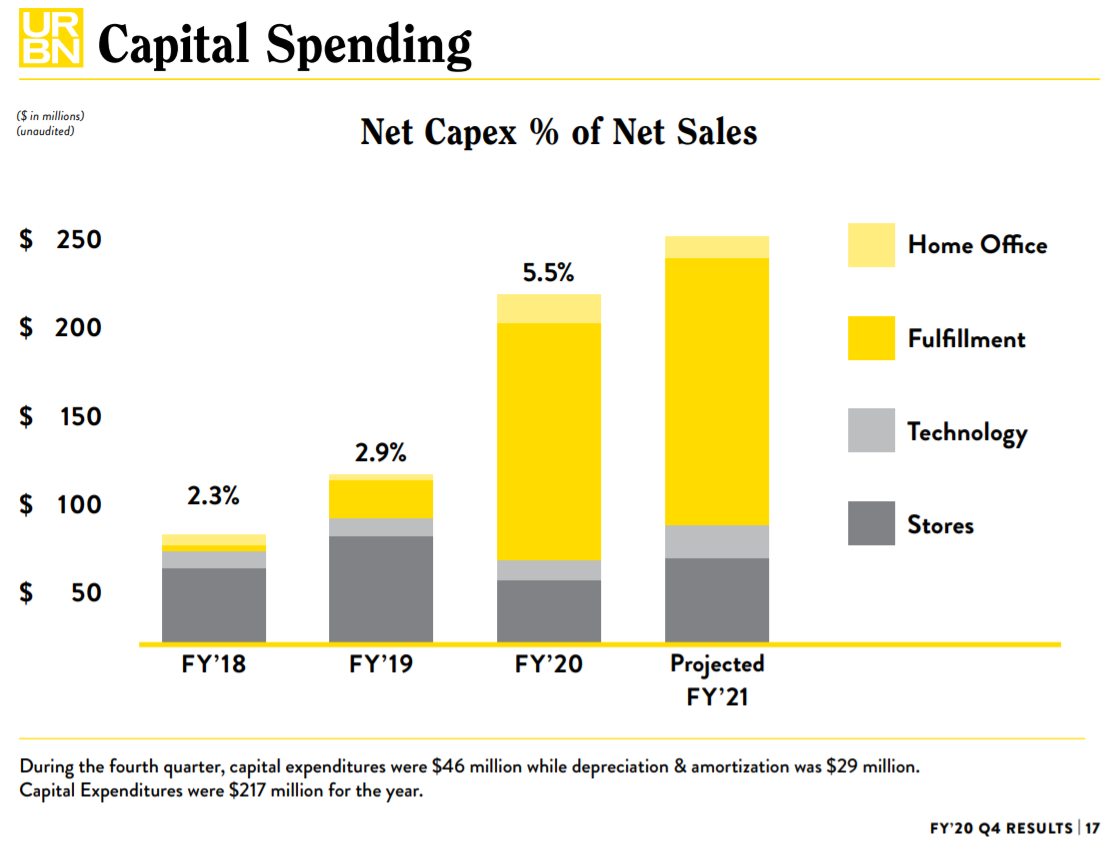
Urban Outfitters spent over $100 million on fulfillment improvements last year, and expects to do a similar amount of spending this year. This money buys the company additional distribution centers, as well as the support infrastructure to deliver product at high volumes efficiently. Urban Outfitters may have been a bit late to the game when it comes to investing in digital fulfillment, but it is taking it on properly at this point, and I think the timing couldn’t be better.

