
Summary
- The Grassroots acquisition is accretive and opens up new outlets for Curaleaf.
- While we like the deal, we're now more cautious about regulatory intervention.
- This could add volatility in the near future, so cautious optimism should be exercised.
Grassroots Acquisition
Our first article focused on the massive Select acquisition and the opportunity it presented for Curaleaf (OTCPK:CURLF). Yesterday, Curaleaf surprised investors again and made an announcement to acquire Grassroots (GR Companies, Inc.) for a total consideration of $875mm. This accretive acquisition adds 61 dispensary licenses, 20 dispensaries in operation, and 17 cultivation and processing licenses across 12 states, 7 of which expands Curaleaf's presence into new states. Grassroots generated $12mm in sales in Q1 2019, with growth primarily focused in Illinois and Pennsylvania.
Source: Grassrootscannabis.com
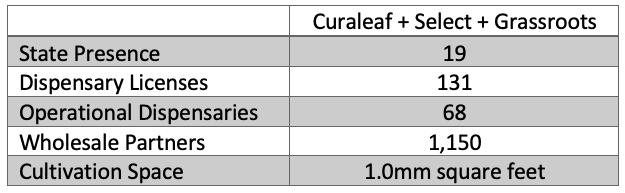
The table below summarized the pro-forma company's retail presence:
Source: Company presentation
There's no doubt about the accretive nature of this acquisition. Management explained that Grassroots' margins are more similar to those of Curaleaf versus Select's margins. We feel confident that the pro-forma company, with the accretive assets of Grassroots, will have better margins than its predecessor. Management is expected to provide pro-forma guidance for 2019 and 2020 in the next earnings call.

